Construction Industry Scheme
CIS Tax Returns for Subcontractors
CIS Deductions
How CIS Deductions Work
If you work under the Construction Industry Scheme (CIS), your contractor takes deductions from your payments and passes them to HMRC.
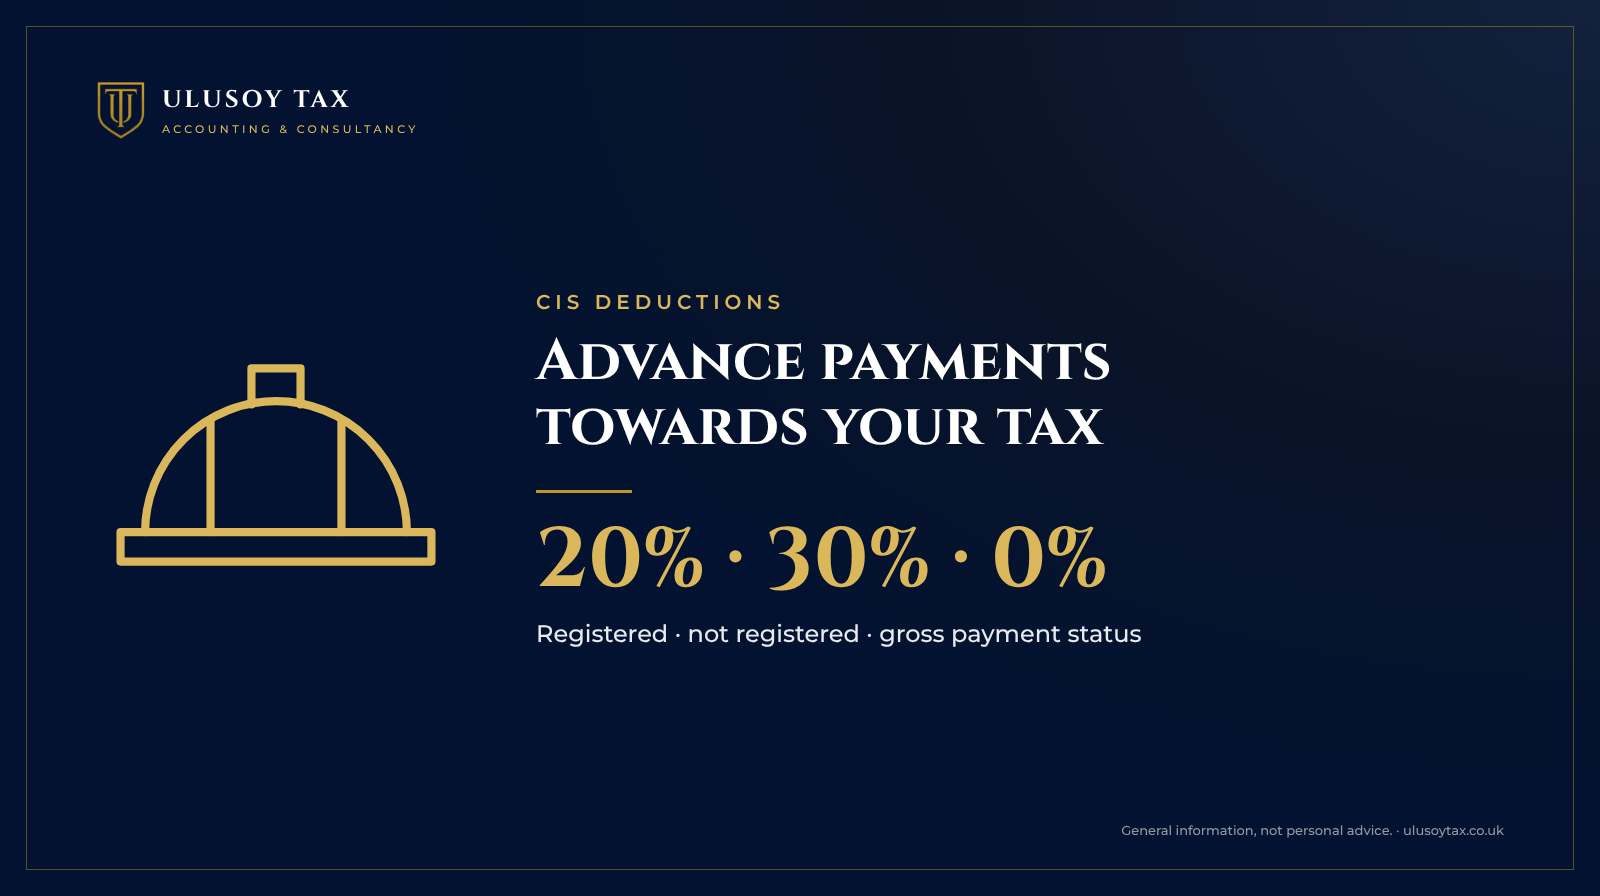
| Your status | Deduction |
|---|---|
| Registered for CIS | 20% |
| Not registered | 30% |
| Gross payment status | No deduction |
Registration is online. If you do not have a UTR, you register for Self Assessment first and choose “working as a subcontractor”.
Deductions Are Advance Payments
CIS deductions count as advance payments towards your tax and National Insurance. On your Self Assessment return you report your gross earnings, business expenses and CIS deductions. HMRC works out what you owe and takes the deductions off. If more was deducted than you owe, HMRC repays the difference; if less, you pay the balance.
For the 2025 to 2026 tax year, the online return and payment deadline is 31 January 2027.
Records and Gross Payment Status
Records You Need
- Monthly CIS payment and deduction statements from each contractor
- Invoices and bank statements for any non-CIS work
- Receipts for tools, equipment, protective clothing and safety equipment
- Vehicle costs or a business mileage log
- Phone bills, for the business share
If a statement is missing, ask the contractor for it. The deduction totals on your return should match the statements.
Gross Payment Status
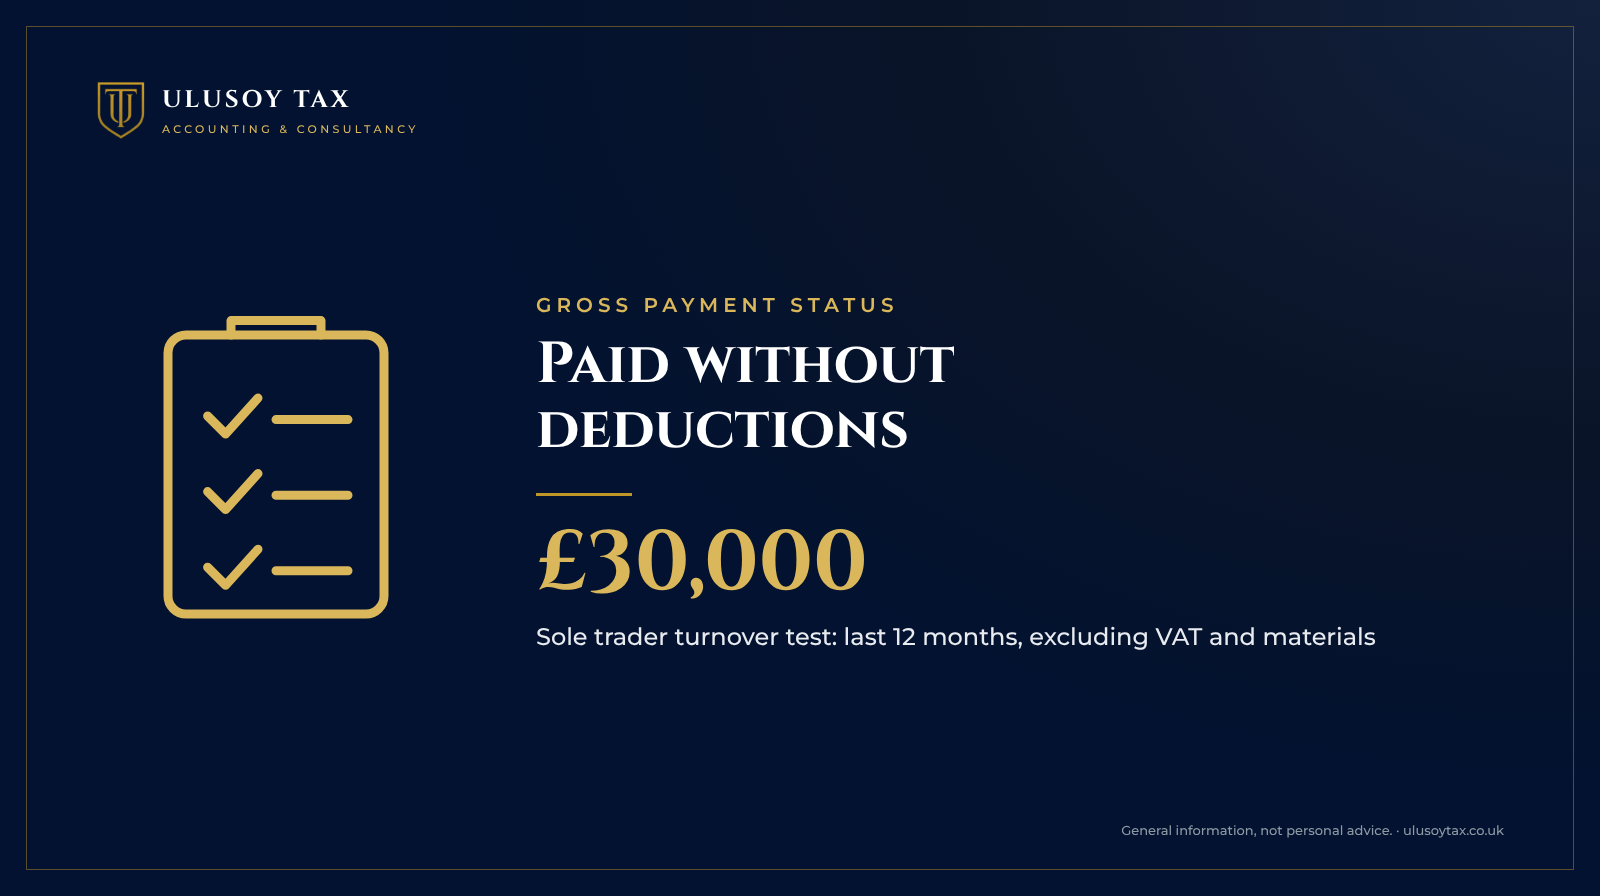
With gross payment status, contractors pay you without deductions. To qualify, your business must do construction work in the UK, be run through a bank account, and have paid tax and National Insurance on time in the past. HMRC also looks at your turnover for the last 12 months, excluding VAT and materials:
| Business type | Minimum turnover |
|---|---|
| Sole trader | £30,000 |
| Partnership | £30,000 for each partner, or £100,000 in total |
| Limited company | £30,000 for each director, or £100,000 in total |
HMRC reviews gross payment status every year, so returns and payments need to stay on time.
Contractors and Limited Companies
If You Pay Subcontractors
- Verify each subcontractor with HMRC before you pay them
- Give each subcontractor a payment and deduction statement within 14 days of the end of each tax month
- File your monthly CIS return by the 19th of the following month
- Since 6 April 2026, file a nil return for any month with no payments, unless you told HMRC in advance
Limited Company Subcontractors
If your limited company has CIS deductions taken, they are claimed back through the company’s monthly payroll submissions (EPS), not the Corporation Tax return. HMRC takes them off what the company owes in PAYE tax and National Insurance.
How I Can Help
- Registering for CIS and Self Assessment, and getting your UTR
- Preparing and filing your Self Assessment return with CIS deductions
- Monthly CIS returns and statements for contractors
- Claiming CIS deductions through payroll for limited companies
Message me on WhatsApp, in English or Turkish, or get an instant quote with the pricing calculator.
This page is general information based on GOV.UK guidance as of October 2026. It is not personal advice.